
You found the condo. You had an offer accepted. Then your loan officer called and said the project is non-warrantable, and the deal you thought was done suddenly needs a different loan, a bigger down payment, or both.
Here’s the part that catches most people off guard. Nothing is wrong with you. Your credit is fine, your income is fine, your down payment is fine. A non-warrantable condo in Michigan fails because of something the building is doing, and it’s usually something you had no way to see from the listing.
There’s also good news, and it’s recent. Fannie Mae changed several condo project rules on August 3, 2026, and one of those changes made a lot of previously ineligible Michigan projects financeable again. We’ll get to that, including a file we closed because of it.
What is a non-warrantable condo?
A non-warrantable condo is a unit in a project that doesn’t meet the project-level standards set by Fannie Mae, Freddie Mac, FHA, or VA. The borrower can be perfectly qualified and the loan still gets denied, because with a condo the lender underwrites two things: you, and the condominium project. Fail either one and there’s no conventional loan.
That second review is the whole difference between buying a condo and buying a house. On a single-family home, your lender looks at your credit, your income, and an appraisal. On an attached condo, your lender also pulls the master deed, the bylaws, the HOA budget, the reserve study, the master insurance policy, and a completed HOA questionnaire, then runs the project through Fannie Mae’s Condo Project Manager (CPM) to confirm it’s eligible.
Think of it like a co-signer you never met and can’t negotiate with. Your finances qualify. Your co-signer’s might not.
Riverbank has been financing Michigan condo loans out of Grand Rapids for years, including the projects other lenders turn down, so most of what follows comes from files we’ve actually worked.
What makes a Michigan condo non-warrantable?
A Michigan condo becomes non-warrantable when the project trips one of Fannie Mae’s ineligibility rules. These are published in the Fannie Mae Selling Guide, section B4-2.1-03, and they’re more specific than most people expect. Here are the ones that actually show up:
- Commercial space over 35%. If more than 35% of the project’s square footage, or of the building the project sits in, is retail, office, restaurant, hotel, or rental apartments, the project is out. Ground-floor retail is fine. A residential floor or two stacked on four floors of commercial is not.
- One owner holding too many units. In a project of 21 or more units, no single entity can own more than 20% of them. In projects of 5 to 20 units, the cap is 2 units. Note this is single-entity ownership, which is a different test from overall investor concentration, and it’s one of the rules that did not go away in August 2026.
- Hotel-like operation. Daily or weekly rentals, a front desk, rental pooling agreements, housekeeping, a management company that also books short-term stays, or the word “resort” in the project name. Fannie Mae calls these condotels and won’t buy the loan.
- Litigation over safety or structure. If the HOA is party to a lawsuit involving safety, structural soundness, habitability, or functional use of the project, that’s disqualifying. Minor litigation is survivable, including neighbor disputes and cases where the insurer is defending and expected damages stay under 10% of the association’s funded reserves.
- Critical repairs left unfunded. Any unfunded repair that should be done in the next 12 months and costs more than $10,000 per unit makes the project ineligible. So does an evacuation order, advanced deterioration, active water intrusion, or a failed jurisdictional safety inspection.
- Business income the HOA shouldn’t have. If more than 10% of the association’s budgeted income comes from running a restaurant, health club, or spa open to the public, the project is out.
- Termination or insolvency. A project that has voted to dissolve, deconvert, or file bankruptcy is ineligible, including while the vote is still in progress.
Condo Financing Guideline Changes on August 3, 2026
Fannie Mae issued Lender Letter LL-2026-03 in March 2026 and folded it into the Selling Guide in August. Freddie Mac made matching changes. Three of them affect Michigan condo buyers directly, and they cut in both directions.
Investor concentration limits were removed. This is the big one. A project with a high share of rentals rather than owner-occupants used to fail review. That limit is gone for established projects. If a lender told you in early 2026 that your Michigan condo project was non-warrantable because too many units were rented, that answer may simply be out of date.
Limited Review was eliminated. For applications dated on or after August 3, 2026, established condo projects can no longer use the streamlined Limited Review that skipped the financial analysis. It’s Full Review or a Waiver of Project Review now. Industry estimates put Limited Review at somewhere between 40% and 65% of condo transactions before the change, so this affects a lot of files. Practically, it means your lender needs more HOA documents than they did last year, and the HOA needs to actually produce them.
Reserve funding requirements went up. The minimum reserve allocation is rising from 10% to 15% of the association’s annual budgeted income, reserve studies have to use the highest recommended funding level rather than a baseline plan, and a study older than 36 months won’t pass. Underfunded Michigan associations are going to feel this, and some will raise dues or levy assessments to stay financeable.
A Michigan closing that only worked because of the change
Here’s one from our own pipeline. A buyer came to us after another lender told her the condo project she was under contract on was non-warrantable. The reason was investor concentration: too many units in the complex were rentals rather than owner-occupied. The option she’d been given was a portfolio loan with a higher rate and a larger down payment, and she was close to walking away from the unit entirely.
We re-reviewed the project under the guidelines that took effect August 3, 2026. Fannie Mae had removed the investor concentration limit, and the single thing that made that project ineligible a few months earlier no longer applied. Nothing about the building changed. The rule did. She closed on a conventional mortgage at conventional pricing and kept the difference.
The takeaway matters more than the file: if you were told a Michigan condo was non-warrantable before August 2026, get the project re-run before you accept that answer. It costs nothing to check.
If your Michigan condo is detached, this probably doesn’t apply to you
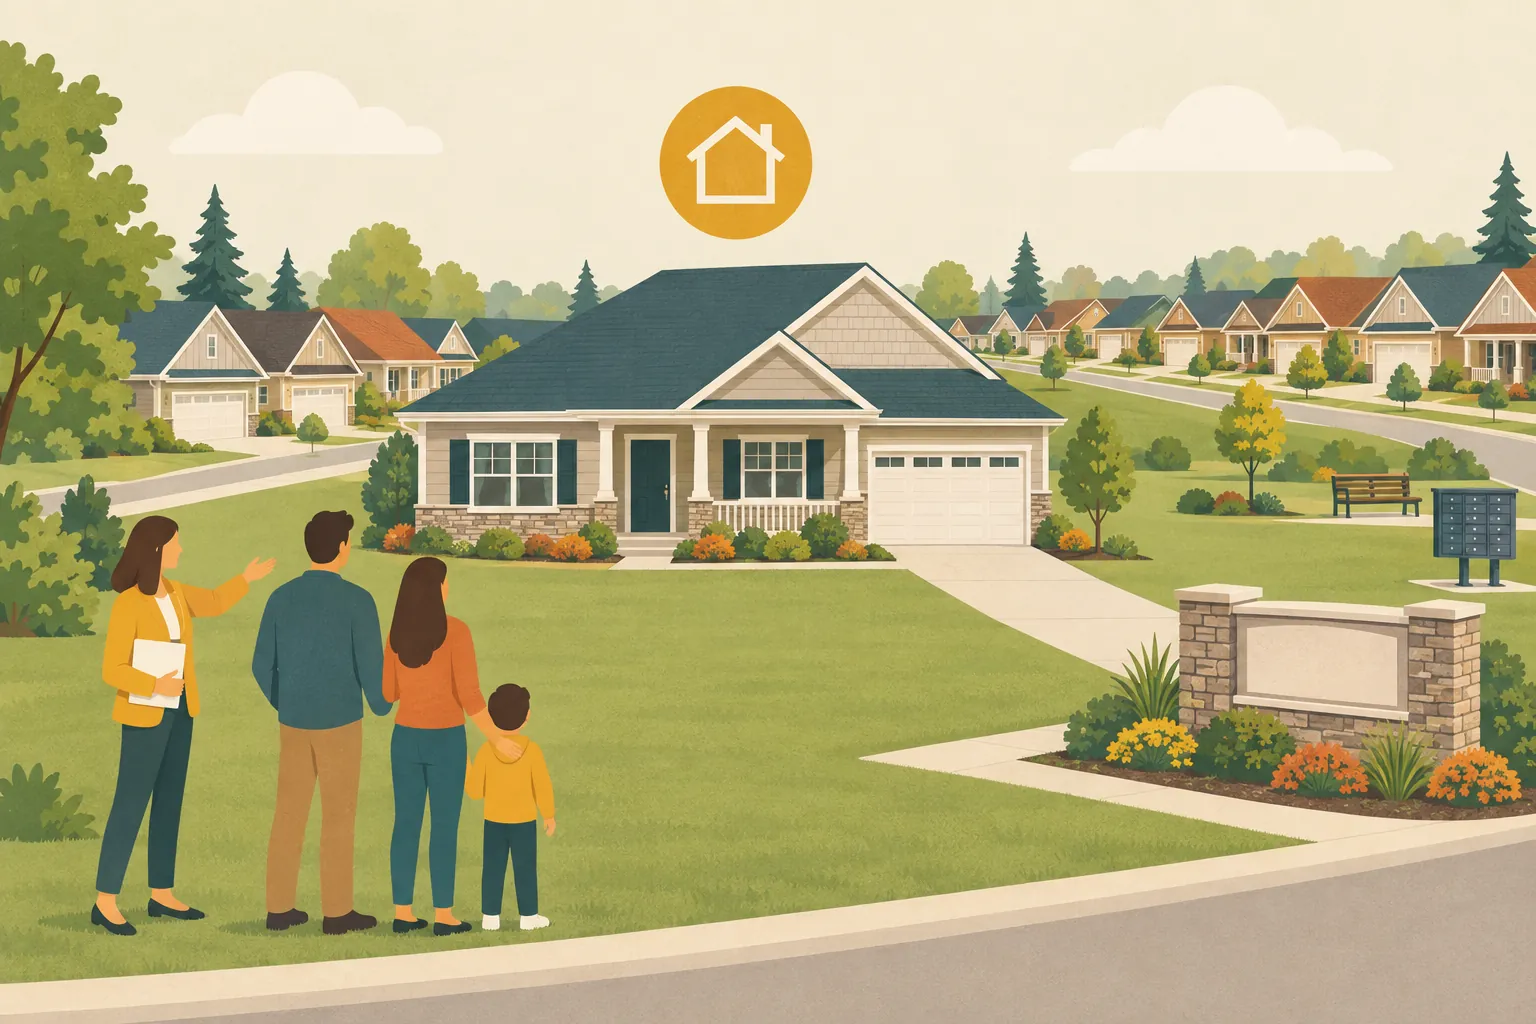
Michigan is unusual here, and it works in buyers’ favor. Michigan developers have spent decades platting detached single-family subdivisions as condominiums under the Michigan Condominium Act (PA 59 of 1978), because it’s faster and cheaper than platting a subdivision. The state calls these site condominiums: a condo development made up of single-family detached homes, each on its own lot, each owner responsible for their own yard.
Fannie Mae treats a site condo as a detached condo. Detached condos get an automatic waiver of project review, in new and established projects alike. No Full Review, no commercial space calculation, no reserve analysis.
VA treats Michigan site condos the same way, and has since 2018. VA Circular 26-18-12 waived the condo approval process for site condominiums in Michigan specifically, so they’re processed as single-family detached residences instead of going through project approval. If you’re using your VA benefit, here’s how Michigan site condo approval works for VA loans.
The most common version of this: a buyer in Novi or Grand Rapids Township sees “condo” on the listing for what is visibly a standalone house with a driveway and a lawn, reads an article about non-warrantable condos, and calls braced for bad news. The unit shares no walls with anything. It’s a site condo. Project review is waived and it’s a normal conventional loan.
A few conditions still apply even with the waiver. The project can’t be flagged Unavailable in CPM, can’t be a condotel or timeshare, and the unit still needs a normal appraisal and proper insurance. The same waiver also covers 2-to-4-unit condo projects, and 5-to-10-unit projects that aren’t part of a larger development or master association.
So before you assume you have a problem: is the unit attached to anything? If not, you very likely don’t.
The Michigan buildings that do still get flagged
Even after the August 2026 changes, four patterns account for most non-warrantable findings in Michigan, and they cluster by geography and building type.
Up North resort condos. The situation that comes up most: a buyer wants a place in Traverse City, Harbor Springs, or Petoskey, and the project runs an on-site rental program booking nightly stays through a resort management company. Most buyers assume that since they’re buying it as a second home, the rental program is somebody else’s business. It isn’t. Fannie Mae looks at how the project operates, not how you intend to use your unit, and nightly rentals plus resort management is the textbook condotel profile. This is the most common non-warrantable scenario in Michigan and the hardest to fix, because nobody is unwinding a rental program to close your loan.
Mixed-use lofts downtown. Converted buildings in Detroit, Grand Rapids, Ann Arbor, and Kalamazoo often have commercial square footage that runs past 35%. Here’s where it usually goes sideways: the calculation covers the whole building, not just the condo project, and leased apartments count as commercial space even though people live in them. A building with two floors of condos, three floors of rental apartments, and a restaurant can blow the limit easily.
Unfinished phases. Michigan site condo and attached condo projects are typically built in phases, and plenty of projects started before 2008 still carry undeveloped land and “need not be built” units in the master deed. Incomplete phases and unfinished common elements are a standard project review problem, and the Condominium Act’s own developer withdrawal deadlines can leave a project’s status genuinely unclear.
Reserves and deferred maintenance in older stock. Michigan has a lot of 1970s and 1980s condo inventory with original roofs, parking decks, and balconies. A borrower we see often is the one under contract in a well-kept 1980s project that simply never raised dues enough, now facing a special assessment for a roof replacement. If that work is unfunded, needed within 12 months, and runs over $10,000 per unit, the project is ineligible until it’s resolved or funded. With Limited Review gone and reserve minimums climbing, this category is the one to watch in 2027.
Fannie Mae’s ineligible list, and why you can’t look yourself up
When a project fails review, Fannie Mae flags it “Unavailable” in Condo Project Manager, and no lender can sell a loan on any unit in that project. This is what real estate agents call the condo blacklist. The formal name is the ineligible projects list.
Two things about it are worth knowing before you shop.
First, it grew enormously after the 2021 Surfside collapse in Florida. A dataset shared with the Wall Street Journal showed 5,175 condominium and homeowner associations on the list as of March 2025, up from a few hundred before Surfside, with roughly 1,438 in Florida alone. Michigan is nowhere near Florida’s numbers, but the tightening was national, and older Michigan projects with thin reserves or insurance gaps have been caught up in it.
Second, it’s confidential. Fannie Mae doesn’t publish it. CPM access is restricted to lenders, and buyers, sellers, and agents usually find out a building is flagged only when a loan gets denied. There is no website where you type in your condo’s name.
The practical move: have a lender run the project through CPM before you write an offer, not after. It takes a day or two. Ask your agent to request the HOA’s most recent budget, reserve study, and any special assessment or litigation disclosures at the same time. Send us the project name and we’ll check it.
How to finance a non-warrantable condo in Michigan
When a Michigan condo project is genuinely non-warrantable, financing it means leaving the conventional market. The loan gets held on a lender’s own balance sheet or sold to a non-agency investor, which means the lender sets its own rules, and those rules are stricter on you because they’re looser on the building.
| Option | How it works | Typical tradeoff |
|---|---|---|
| Portfolio loan | A bank or credit union funds the loan and keeps it. No agency guidelines to satisfy. Riverbank offers portfolio non-warrantable condo loans in Michigan. | May be a higher rate than conventional, a larger down payment, and sometimes an ARM rather than a 30-year fixed. |
| Non-QM loan | Sold to private investors instead of Fannie or Freddie. Built for exactly this, including condotels in some cases. | Highest cost of the group, with higher credit score floors and heavier reserve requirements. |
| FHA Single-Unit Approval | FHA can insure one unit in a project that isn’t FHA-approved. Requires a completed project with at least 5 units, no more than 10% of units already FHA-insured (max 2 in projects under 10 units), 50% owner-occupancy, and commercial space at or under 35%. See our FHA mortgage page. | Low down payment survives, but the project still has to clear those tests. Doesn’t help with condotels or litigation. |
| VA loan | VA maintains its own approved condo list, separate from FHA and Fannie Mae. A project Fannie won’t take can still be VA-approved. Details on our VA loan page. | Eligible veterans and service members only. Worth checking, since people assume a Fannie denial closes the VA door too. |
| DSCR loan | If you’re buying the unit as a rental, a Michigan DSCR loan qualifies you on the property’s rental income rather than your personal income, and these programs are often more flexible on project type. | Investment properties only. Higher rate and down payment than an owner-occupied loan. |
| Wait for the project to cure | Some flags are curable. Litigation settles. A special assessment gets funded. A developer sells down. Or, as of August 2026, the rule itself changes. | Slow and outside your control. Rarely fits a purchase timeline, but it’s the right play for a refinance. |
One workaround most buyers never hear about: the single-entity ownership limit can be waived when your purchase is the thing reducing the concentration. If the single owner holds 49% or less, is actively marketing units for sale, is current on assessments, and the project has no pending special assessments, Fannie Mae allows the exception.
Here’s the version that comes up: an investor who bought units during a slow sales period owns 30% of a 40-unit project and is selling them off one at a time. The first few buyers get denied. Once the numbers line up with the waiver conditions, the same project starts closing conventional loans. Worth having your loan officer ask rather than assuming the door is shut.
When you shouldn’t buy one
Non-warrantable doesn’t mean bad, but it does mean smaller. Here’s the honest tradeoff nobody selling you a loan leads with: the pool of buyers who can purchase your unit later is the same narrow pool you’re in right now.
If you’re planning to sell in three to five years, that matters a lot. Conventional financing is how most buyers buy. Take it away and your future buyer is paying more, putting more down, or paying cash. That usually shows up in the price you get.
Think hard before buying if any of these describe you:
- You need to sell within five years.
- Your down payment is small and stretching further would drain your reserves.
- The flag is structural or litigation-related, which means the project’s underlying problem is unresolved and may come back as a special assessment you pay for.
- You’re buying it as an investment and the numbers only work at a conventional rate.
It makes much more sense if you’re buying a place you plan to hold for a decade, you have real equity to put in, and the reason for the flag is administrative rather than physical. A project flagged for commercial square footage isn’t falling down. A project flagged for advanced deterioration might be.
Frequently asked questions
How do I find out if a condo is warrantable before I make an offer?
Ask a lender to run the project through Fannie Mae’s Condo Project Manager and review the HOA questionnaire, budget, reserve study, and master insurance policy. Most lenders will do a preliminary check in a day or two. There is no public database you can search yourself, and the association often doesn’t know its own status.
Did Fannie Mae’s August 2026 changes make it easier to buy a condo?
In one important way, yes. Fannie Mae removed investor concentration limits for established projects effective August 3, 2026, so a high percentage of rentals no longer makes a project ineligible on its own. In other ways it got harder. Limited Review was eliminated the same day, meaning nearly every condo file now needs a Full Review with complete HOA financials, and reserve funding requirements are rising from 10% to 15% of the annual budget.
Are Michigan site condos non-warrantable?
No. A Michigan site condo is a detached condominium, and Fannie Mae waives project review for detached condo units in both new and established projects. If the unit shares no walls, ceilings, floors, garages, or breezeways with a neighboring unit, the project-level tests generally don’t apply. The unit still needs a standard appraisal, proper insurance, and the project can’t be flagged Unavailable in CPM.
Can a non-warrantable condo become warrantable later?
Yes, and it happens regularly. Litigation settles, a special assessment funds the repair, a developer finishes the final phase, an investor sells down below the single-entity limit. Guidelines change too, as the August 2026 investor concentration update showed. Once the underlying issue is resolved, the project can be re-reviewed and units can qualify for conventional financing again. If you bought with a portfolio loan, that’s your refinance opportunity.
Does FHA finance non-warrantable condos in Michigan?
Not in the general sense. FHA runs its own project approval list, and a project can be FHA-approved even if Fannie Mae won’t take it. FHA also offers Single-Unit Approval, which insures one unit in an unapproved project, but the project still has to clear FHA’s own tests on owner-occupancy, commercial space, and FHA-insured concentration. A condotel or a project in structural litigation won’t qualify either way.
Who pays for the condo questionnaire?
The buyer usually does, indirectly. Michigan HOAs and management companies typically charge a fee to complete a lender questionnaire, and it lands on the closing statement. Order it early. A slow management company is one of the most common causes of a delayed condo closing, and with Limited Review retired, lenders need more documents from the HOA than they used to.
What to do next
One takeaway: find out what your building’s status actually is before you fall in love with the unit. And if you got a non-warrantable answer before August 2026, get it re-checked, because the rules moved and the answer may have moved with them.
Send us the address and the HOA’s contact information and we’ll run the project, tell you where it stands, and lay out which financing paths are open before you’re up against a closing date. Call 800-555-2098 or apply online to get started. You can also compare payments with our mortgage calculator or check today’s Michigan mortgage rates.